Alacriti Orbipay Payments Hub Review 2026: Features, Pricing, Pros & Cons
Review summary
Alacriti Orbipay Payments Hub is a cloud-native platform for banks and credit unions that unifies multiple payment rails under one system with ISO 20022 support and intelligent routing.
Alacriti Orbipay Payments Hub serves as a cloud-native payments orchestration platform built specifically for banks and credit unions. Launched with a focus on instant payments infrastructure, it combines initiation, processing, settlement, and analytics across multiple rails in a single hub. Institutions use it to handle RTP, FedNow, ACH, Fedwire, Visa Direct, and Zelle without replacing existing core systems.
Core Capabilities and Supported Payment Rails
The platform operates on microservices architecture with open APIs and native ISO 20022 messaging. It includes intelligent routing that evaluates speed, cost, reliability, and liquidity before directing each transaction. A configurable rules engine allows institutions to set business logic for exception handling, fraud screening, and compliance checks including real-time OFAC screening. Real-time dashboards provide visibility across all rails, while analytics track volumes, costs, and settlement positions.
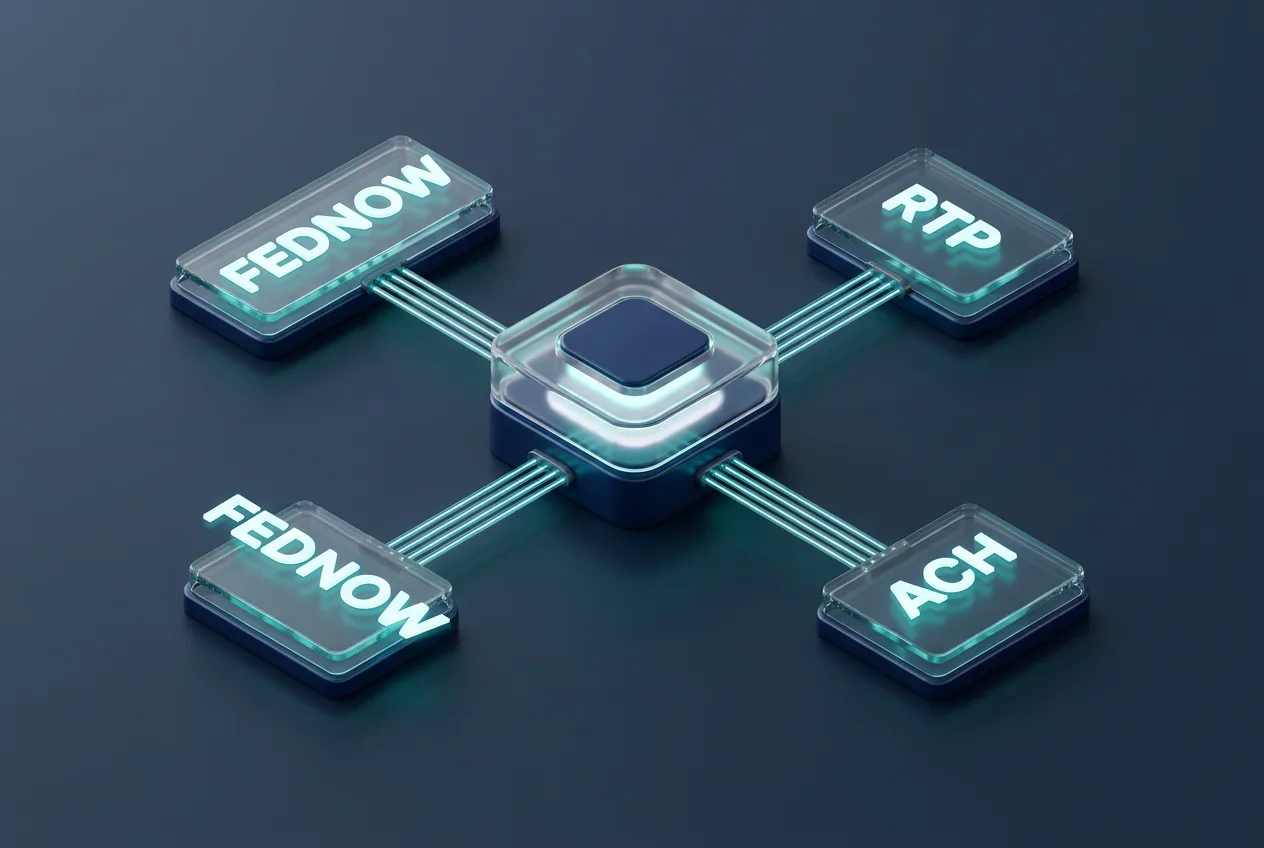
Supported domestic rails include The Clearing House RTP network, FedNow Service, Fedwire, ACH with same-day and next-gen options, Visa Direct, and Zelle for consumer, SMB, and disbursement use cases. Cross-border payments route through partner international wires and Visa Direct. The system activates rails on a grow-as-you-go basis so institutions add capabilities without full upfront commitments. Integrations cover most major core banking and digital banking platforms and remain core-agnostic.
Practical use cases include P2P transfers, account-to-account moves, loan disbursements, bill payments, and corporate payouts. The platform processed more than 96 million transactions representing roughly 233 billion dollars annually as of late 2025, equating to 6.5 to 7 percent of U.S. instant payments volume at that time.
Pricing Structure, Implementation, and Security
Pricing follows a custom enterprise model based on enabled rails, transaction volume, number of channels, fraud modules, and required integrations. No public rate cards exist; institutions request proposals that also cover implementation scope. The grow-as-you-go rail activation model reduces initial outlay by allowing phased enablement. Reported implementation timelines range from two to three months for initial rails, as seen in deployments at Royal Credit Union and Arizona Financial Credit Union.
Security features center on real-time fraud and compliance screening plus configurable exception workflows. The platform holds recognition for cloud-native design in the 2026 ABA/Datos Insights Payment Hubs assessment focused on community banking. Alacriti reports 98 percent client retention and serves approximately 14 of the top 100 U.S. financial institutions along with 25 percent of large credit unions.
Ease of use centers on unified dashboards that replace multiple rail-specific interfaces. Institutions report reduced manual intervention, with one case study noting roughly 40 percent lower wire handling costs after modernization. Technical requirements include standard API connectivity and existing core integration points; no rip-and-replace of legacy systems is required.
User Feedback, Comparisons, and Known Limitations
Public ratings include 5.0 out of 5.0 on Gartner Peer Insights and 10 out of 10 on TrustRadius. Case examples highlight rapid activation such as Royal Credit Union going live with instant payments in under three months and processing 15.5 million dollars shortly after. Veridian Credit Union and ABNB Federal Credit Union reported early adoption success with measurable volumes in the first months. Common positive notes focus on responsive support, on-time delivery, and unified reporting across rails.
Limitations include the absence of publicly itemized total cost of ownership figures and lower volume of independent reviews compared with larger vendors. Some rails activate sequentially under the grow-as-you-go approach, and cross-border functionality receives less emphasis than domestic instant rails. Detailed competitor data remains limited in public sources, though the platform differentiates through single-API access to both FedNow and RTP alongside strong ISO 20022 support.
Overall the system suits institutions seeking to consolidate multiple payment channels while maintaining existing core infrastructure. Its documented strengths lie in configurability, rapid rail activation, and measurable operational savings for high-volume users.
Frequently asked questions
What payment rails does Alacriti Orbipay Payments Hub support?
It supports RTP from The Clearing House, FedNow Service, Fedwire, ACH including same-day options, Visa Direct, and Zelle. Cross-border options route through partner wires and Visa Direct.
Is Alacriti Orbipay Payments Hub pricing publicly available?
No public pricing exists. Costs are custom and determined by enabled rails, volume, channels, fraud modules, and integrations. Institutions receive tailored proposals.
How long does implementation of Alacriti Orbipay Payments Hub typically take?
Reported timelines range from two to three months for initial rails. Examples include Royal Credit Union going live in under three months and Arizona Financial Credit Union completing wire modernization two months ahead of schedule.
What security features does the platform include?
It provides real-time OFAC screening, configurable fraud and risk tools, exception workflows, and ISO 20022-native processing across rails.
Comments 9